Melbourne Property Market 2026: What Recent Price Falls Mean for Buyers

Short answer: a Melbourne property market recovery is not yet showing up in the headline numbers. The total value of Victorian dwellings fell 1.6 percent in the June quarter 2026 [1], the RBA says prices have fallen in most capital cities [2], and rates rose again in 2026 [3]. But some of the conditions that usually come before a rebound are in place: strong population growth [4], rising approvals that will take years to complete [5], government incentives [6] and new price transparency rules [7]. For buyers, that makes 2026 a market to research carefully rather than chase. Our Melbourne buyers agent service can help you separate the signals from the noise.
TL;DR
Values: Victorian dwelling values fell 1.6 percent ($44.3 billion) in the June quarter [1].
Demand: Victoria grew 1.6 percent to 7,154,200 people [4].
Jobs: Victorian unemployment is 5.1 percent, above the national 4.7 percent [8].
Rates: the cash rate is 4.60 percent [3].
Rules: reserve prices must be disclosed 7 days before auction from 1 October 2026 [7].
In this article
What happened from 2025 to 2026
The case for a recovery
The headwinds
Signs to watch for a rebound
Incentives and costs
New rules that help buyers
How to buy well in Melbourne now
A worked example
FAQs, recommended reading and references
What happened from 2025 to 2026
Many commentators in 2025 expected falling rates to lift Melbourne. Instead, the RBA raised the cash rate four times in 2026 to 4.60 percent [3], citing elevated inflation and noting that housing prices had fallen in most capital cities and new loans had declined [2]. Melbourne's consumer prices rose 4.0 percent over the year to September [9]. Nationally, new dwelling loan commitments fell 5.4 percent in the June quarter [10], and the total value of Victorian dwellings fell 1.6 percent [1].
The case for a recovery
Population. Victoria added 109,500 people in the year to March 2026, growth of 1.6 percent [4]. More people need more homes.
Supply needs. The Victorian Government says the state needs to build more homes each year for the next 10 years [11]. Approvals rose 8.9 percent to 5,163 in August 2026 [5], but approvals take years to become completed homes.
Rents. Rents rose 3.6 percent nationally over the year to September [9], which supports investor returns.
Incentives. Duty concessions for first home buyers [12] and off the plan strata homes [6] lower entry costs.

Illustrative image: well located established homes are often first to recover when conditions improve.
The headwinds
Rates and inflation. Higher rates reduce borrowing power, and APRA's 3 percentage point buffer applies to all new borrowers [13].
Jobs. Victorian unemployment was 5.1 percent in September, the highest of the mainland states shown [8].
Business conditions. NAB reported that conditions remain weak in the large eastern states, including Victoria [14].
Investor costs. Land tax applies once total taxable land exceeds $50,000 for individuals [15], and vacant residential land tax rises from 1 percent to 3 percent of capital improved value the longer land stays vacant [16].
Signs to watch for a rebound
Signal | What to look for |
|---|---|
Dwelling values | Quarterly falls slowing or reversing [1] |
Lending | New loan commitments rising [10] |
Rates | RBA statements turning less restrictive [2] |
Jobs | Unemployment easing [8] |
Auctions | Fewer passed in results, though reports are incomplete [17] |
Supply | Completions lagging population growth [4] |
Weekly auction results are useful but do not give a full picture, because not all results are reported and private sales are excluded [17]. Treat any single week's clearance rate with caution.
Incentives and costs
First home buyers in Victoria pay no duty on homes up to $600,000 and reduced duty up to $750,000 [12], and may receive a $10,000 grant for a new home up to $750,000 [18]. Our first home buyer support can help you check eligibility. For other purchases, general duty above $130,000 and up to $960,000 is $2,870 plus 6 percent of the value over $130,000 [19]; on a $900,000 home that is $49,070. The temporary off the plan concession for strata apartments and townhouses applies to contracts before 21 April 2027 and is open to investors [6].
New rules that help buyers
From 1 October 2026, Victorian agents must disclose the seller's reserve price 7 days before auction, publish final sold prices once a sale is unconditional, and use a new Property Price Statement [7]. Underquoting remains illegal [7]. These changes give buyers better price evidence, which matters in a market where values are uncertain.
How to buy well in Melbourne now
Use recent comparable sales and the new price disclosures to set your limit.
Inspect thoroughly: check for structural issues, permits for renovations and bushfire overlays [20].
Private sales usually include a three business day cooling off period [21]; at auction, bidding means accepting the contract terms on display [22].
Compare fixed and variable loans [23] and get personal advice where needed [24].
Consider a licensed buyer's agent, who acts only for you and can access off market homes [25].
Our property search service, due diligence process and auction bidding service all work in Melbourne, and our investment property strategy helps investors decide whether the timing suits them.
A worked example
Consider a hypothetical family buying a $900,000 house in Melbourne's east. The agent's new Property Price Statement and the reserve disclosure 7 days before auction give them clear price evidence. They bid to a limit set by comparable sales and buy just under it, budgeting for $49,070 in duty. They are not betting on a rapid rebound; they are buying a well located home at a fair price in a softer market. This example is illustrative only.
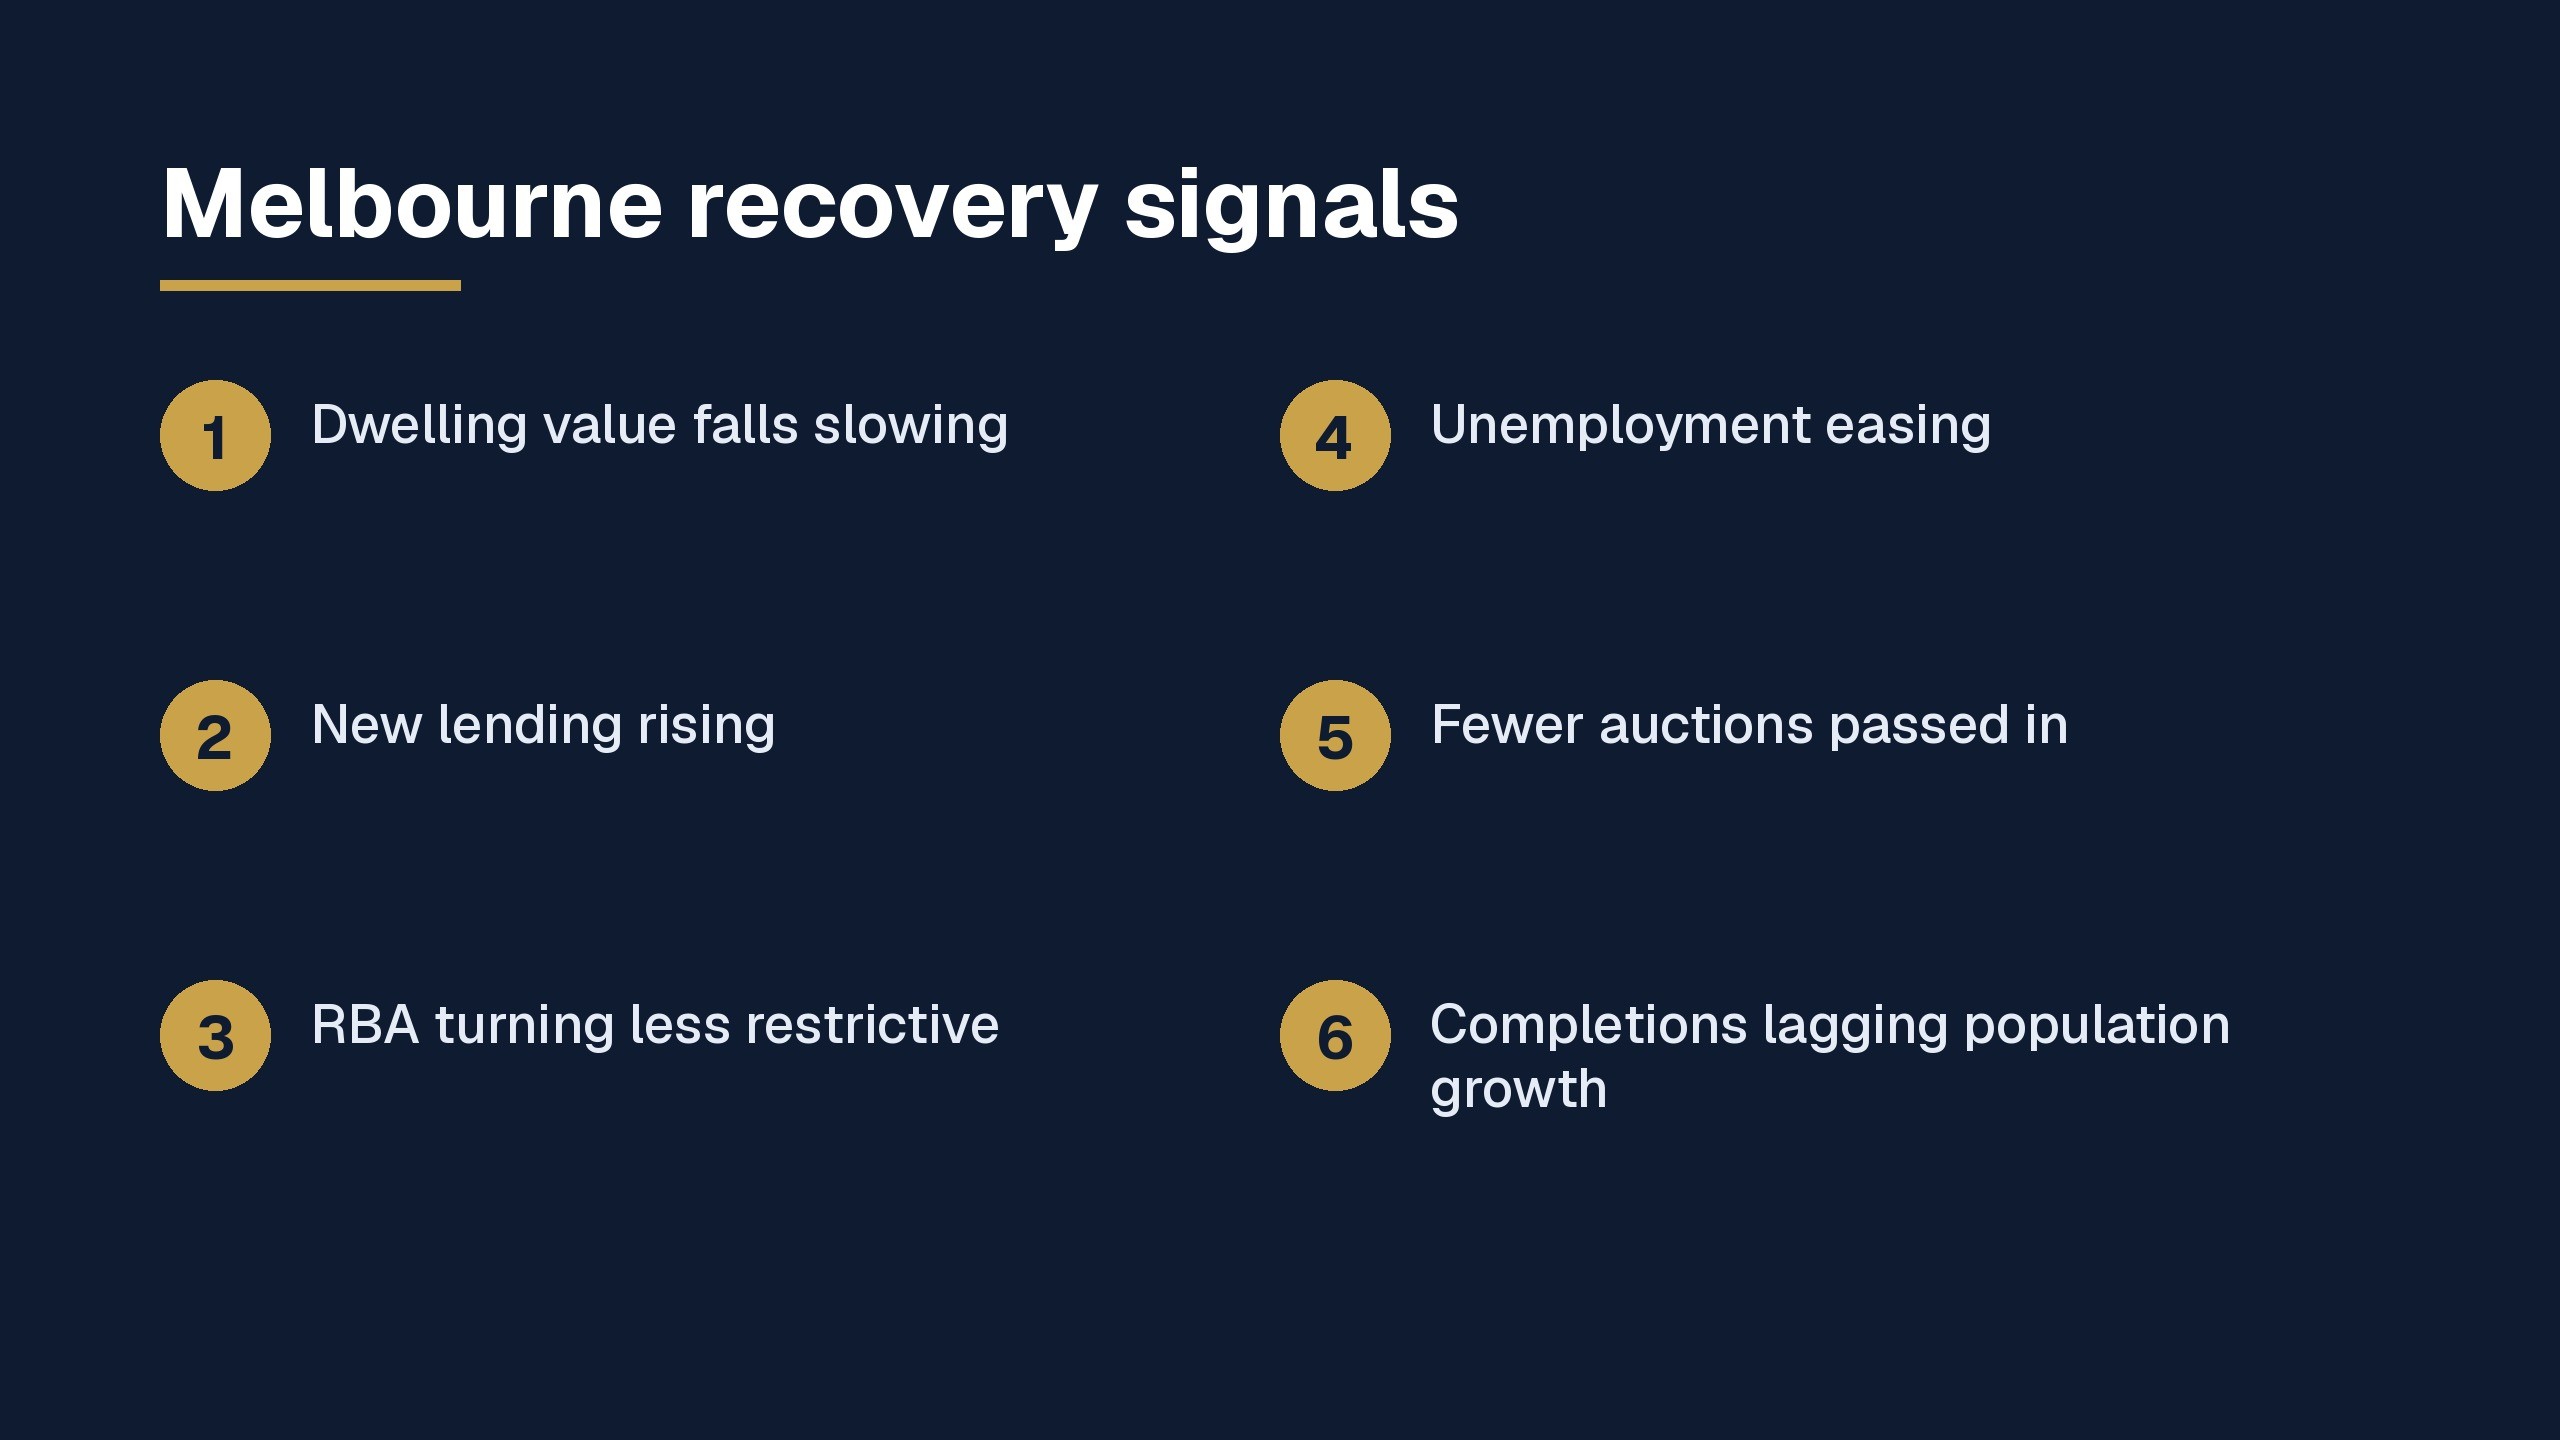
Six signs to watch for a Melbourne recovery.
FAQs
Has the Melbourne market bottomed?
The data does not yet confirm it. Values fell in the June quarter [1]. Watch the signals above.
Is now a good time to buy in Melbourne?
For buyers with secure finance and a long horizon, softer conditions can mean better choice and terms.
Do the new auction rules help buyers?
Yes. Reserve disclosure and sold price publication improve price evidence [7].
Plan your Melbourne purchase
Book a free strategy call or meet our buyers agents in Brisbane who also support interstate buyers.
Recommended reading
References
Australian Bureau of Statistics, Total Value of Dwellings, June Quarter 2026. Supports: Total value of residential dwellings in Victoria fell 1.6 percent ($44.3 billion) in the June quarter 2026.
Reserve Bank of Australia, Statement by the Monetary Policy Board: Monetary Policy Decision (29 September 2026). Supports: Board raised the cash rate target by 25 basis points to 4.60 percent; inflation remains elevated; housing prices have fallen in most capital cities and new housing loans have declined noticeably.
Reserve Bank of Australia, Cash rate target. Supports: Cash rate target 4.60 percent effective 30 September 2026, after rises on 4 February, 18 March and 6 May 2026 (from 3.60 percent).
Australian Bureau of Statistics, National, state and territory population, March 2026. Supports: Victoria population 7,154,200 at 31 March 2026, up 109,500 (1.6 percent) over the year.
Australian Bureau of Statistics, Building Approvals, Australia, August 2026. Supports: August 2026, seasonally adjusted: Victoria total dwelling approvals rose 8.9 percent to 5,163; private sector houses rose 0.5 percent to 3,044.
State Revenue Office Victoria, Strata apartments and townhouses temporary concession. Supports: Temporary off the plan concession for dwellings in strata subdivisions with common property, contracts from 21 October 2024 and before 21 April 2027; deducts construction costs after the contract date from dutiable value; available to all buyers including investors; no value threshold.
Consumer Affairs Victoria, Understanding property prices and underquoting for buyers. Supports: From 1 October 2026 agents must disclose the seller reserve price 7 days before auction, publish the final sold price, and use the new Property Price Statement; underquoting is illegal.
Australian Bureau of Statistics, Labour Force, Australia, September 2026. Supports: Seasonally adjusted September 2026: Victoria unemployment rate 5.1 percent with 3,822,800 employed; Australia 4.7 percent.
Australian Bureau of Statistics, Consumer Price Index, Australia, September 2026 (monthly). Supports: Melbourne all groups CPI rose 4.0 percent over the year to September 2026; rents rose 3.6 percent and new dwelling prices 4.7 percent nationally.
Australian Bureau of Statistics, Lending indicators, June Quarter 2026. Supports: June quarter 2026: 134,225 new dwelling loan commitments (down 5.4 percent); investor commitments 52,599 (down 8.6 percent); first home buyers 29,319.
Victorian Government, More homes for Victorians. Supports: Government says Victoria approved more than 52,000 new homes in the past year and needs to build more homes each year over the next 10 years to increase supply.
State Revenue Office Victoria, First home buyer duty exemption or concession. Supports: First home buyers pay no duty on homes with a dutiable value up to $600,000 and a reduced amount from $600,001 to $750,000; new or established homes or vacant land; must live there 12 continuous months within 12 months of settlement.
Australian Prudential Regulation Authority, APRA maintains current macroprudential policy settings in highly uncertain environment (28 May 2026). Supports: Mortgage serviceability buffer remains at 3 percentage points; high debt to income lending limits unchanged; the buffer helps new borrowers cope with higher expenses and rates.
NAB, Triple squeeze hits business confidence, NAB Monthly Business Survey September 2026. Supports: National business confidence fell 4 points to -13 in September 2026, 18 points below its long run average; conditions held at -1; Queensland conditions fell 4 points and trend conditions are -1, in line with NSW and Victoria; capacity utilisation 82.3 percent.
State Revenue Office Victoria, Costs of buying and owning a property. Supports: Land tax applies when total taxable land value exceeds $50,000 for individuals; home is exempt; vacant residential land tax applies to residential land vacant more than 6 months in a calendar year.
State Revenue Office Victoria, Vacant residential land tax (current rates). Supports: VRLT is 1 percent of capital improved value in the first year, 2 percent in the second and 3 percent for three or more consecutive years.
Consumer Affairs Victoria, Property data. Supports: Weekly auction results do not give a full picture of prices because not all are reported and private sales are excluded; research comparable prices before bidding.
State Revenue Office Victoria, Understanding the First Home Owner Grant. Supports: $10,000 grant for eligible first home buyers buying or building a new home in Victoria worth up to $750,000; must live in it for at least 12 months starting within 12 months.
State Revenue Office Victoria, Land transfer duty, non principal place of residence (current rates). Supports: General rates from 1 July 2021: $2,870 plus 6 percent of value over $130,000 up to $960,000; 5.5 percent of value from $960,000 to $2,000,000; premium rate above $2,000,000.
Consumer Affairs Victoria, Inspect properties before you buy. Supports: Check for structural problems, damp and termites; check the Section 32 statement and council permits for renovations; check whether the property is in a bushfire prone area.
Consumer Affairs Victoria, Buying property by private sale. Supports: Three business day cooling off for residential private sales; offers can be conditional on finance, sale of another property or inspections; sellers must have the due diligence checklist at open inspections.
Consumer Affairs Victoria, Buying property at auction. Supports: By bidding you accept the contract terms on display; no cooling off if a pre auction offer is accepted less than three clear business days before auction.
Moneysmart (ASIC), Fixed vs variable home loan interest rates. Supports: Fixed rates usually set for one to five years then revert to variable; break fees may apply; variable loans often allow extra repayments, offset and redraw; split loans combine both.
Moneysmart (ASIC), Choosing a financial adviser. Supports: Advisers usually give personal advice tailored to your objectives and situation; understand general versus personal advice; not all advisers offer the same services.
Consumer Affairs Victoria, Seek expert advice on property. Supports: A buyer's agent (buyer's advocate) is a licensed estate agent who acts for the buyer for a fee; can access off market properties, assess value, negotiate or bid at auction; an agent cannot act for buyer and seller on the same transaction.
Continue Reading
Explore ideas, trends, and behind-the-scenes stories from our studio.